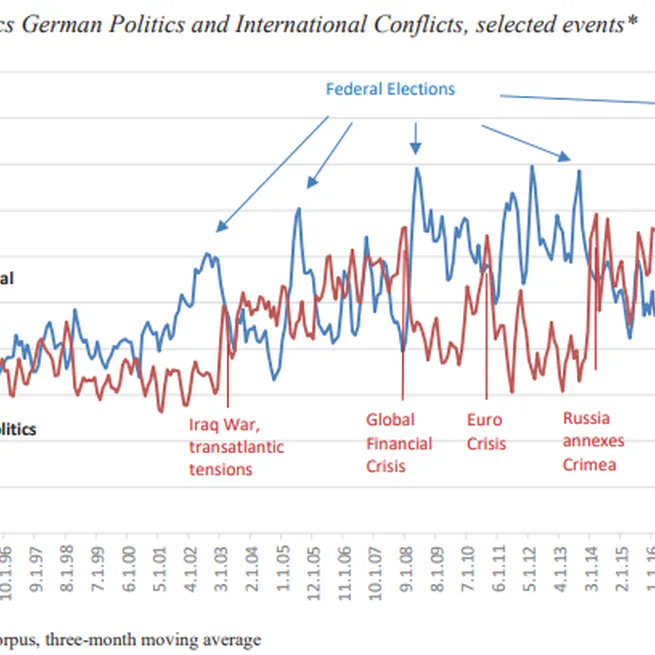
The investment narrative: Improving private investment forecasts with media data
In this paper we use newspaper articles to generate time series that are related to corporate investment and look at their ability to predict its dynamics.
13 Dec, 2021
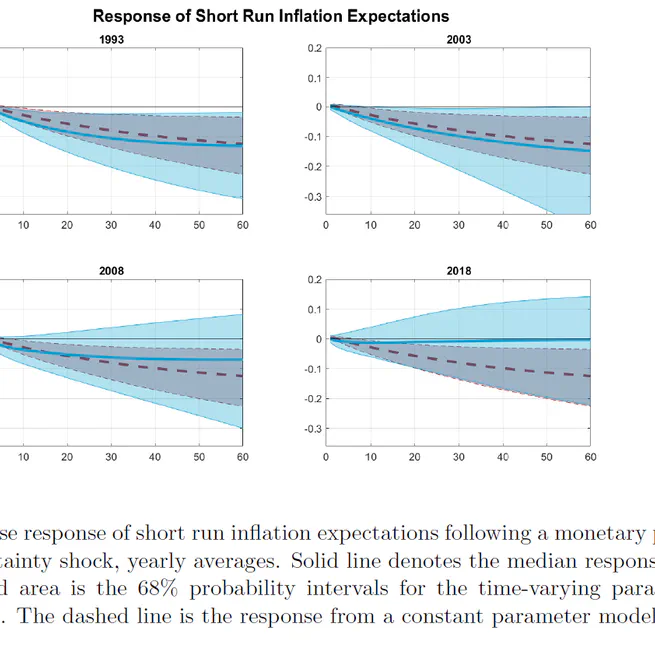
Monetary policy uncertainty and inflation expectations
In this paper we study whether inflation expectations in the U.S. react to changes in monetary policy uncertainty (MPU) as measured through the volatility of monetary policy shocks. We find that while they did, the importance of MPU has diminished and that it has different effects on short versus long-term inflation expectations.
1 Mar, 2021